
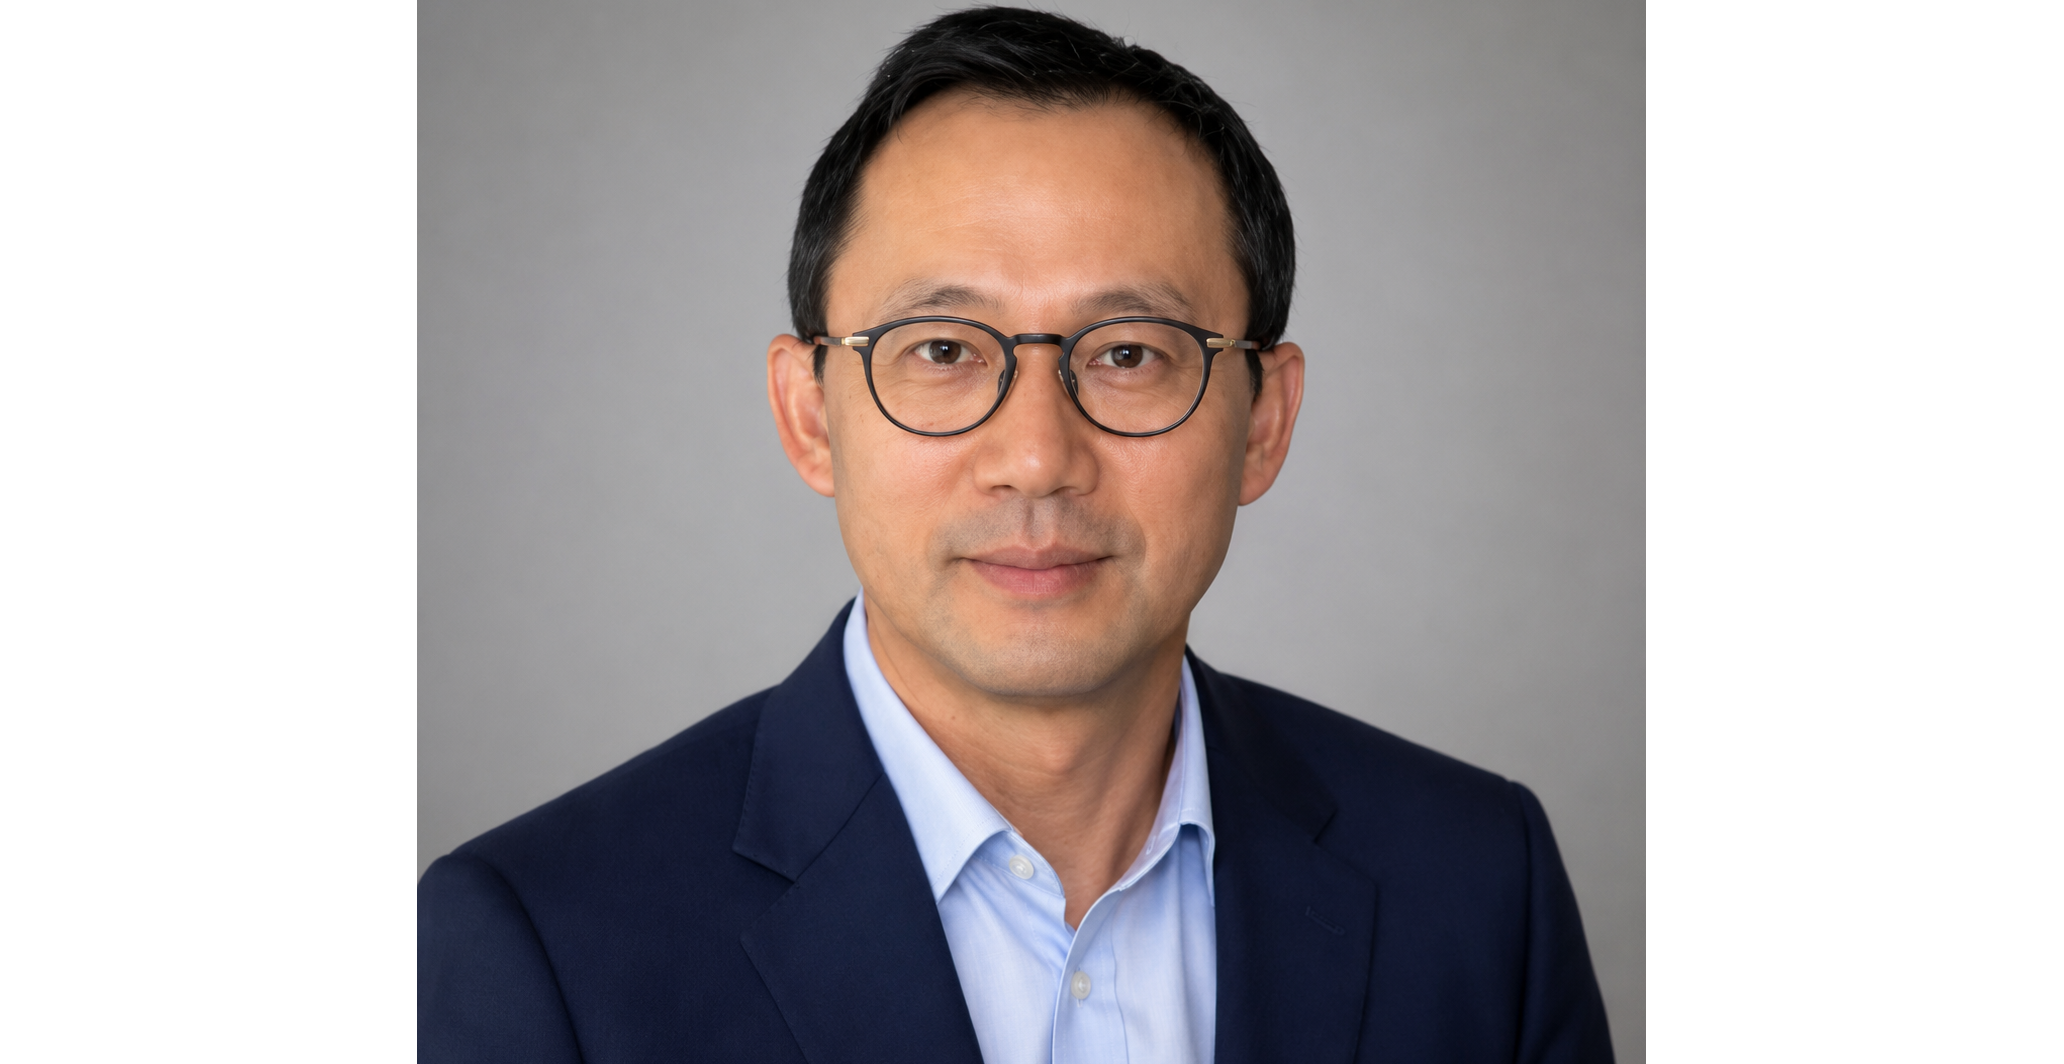
Learning Dynamic Uncertainty via Schrödinger–Bass Bridges: From Generative Modeling to Financial Time SeriesHuyên Pham - Centre de Mathématiques Appliquées, École Polytechnique
Learning Dynamic Uncertainty via Schrödinger–Bass Bridges: From Generative Modeling to Financial Time SeriesHuyên Pham - Centre de Mathématiques Appliquées, École Polytechnique
Modern generative models can be viewed as dynamic transports that transform a simple source distribution into a complex target distribution. In the stochastic setting, the Schrödinger bridge provides a classical and computationally tractable formulation: among all diffusions matching two prescribed marginal laws, it selects the one closest to Brownian motion. However, the classical Schrödinger bridge learns a drift while keeping the volatility fixed, which is restrictive in applications where uncertainty itself is part of the signal, notably in finance.
In this talk, I will introduce the Schrödinger–Bass Bridge, a semimartingale optimal transport problem that interpolates between the Schrödinger bridge and the Bass martingale transport. The resulting optimal dynamics learn both drift and volatility. I will describe the associated Schrödinger–Bass system, its interpretation as a Bass transport of a Schrödinger bridge, and the resulting fixed-point algorithm. I will then discuss applications to generative modeling, first for image synthesis and then for financial time series. In the time-series setting, the method leads to SBBTS, a sequential generative model designed to preserve temporal dependence and stochastic volatility. Numerical experiments illustrate its ability to recover hidden Heston-type volatility and correlation structures and to improve downstream forecasting through synthetic data augmentation.
This presentation has been archived in the TTU Mediasite catalog ...
mediacast.ttu.edu/Mediasite/Play/40e41fa08bed4e82b7561dbe488046981d
In this talk, I will introduce the Schrödinger–Bass Bridge, a semimartingale optimal transport problem that interpolates between the Schrödinger bridge and the Bass martingale transport. The resulting optimal dynamics learn both drift and volatility. I will describe the associated Schrödinger–Bass system, its interpretation as a Bass transport of a Schrödinger bridge, and the resulting fixed-point algorithm. I will then discuss applications to generative modeling, first for image synthesis and then for financial time series. In the time-series setting, the method leads to SBBTS, a sequential generative model designed to preserve temporal dependence and stochastic volatility. Numerical experiments illustrate its ability to recover hidden Heston-type volatility and correlation structures and to improve downstream forecasting through synthetic data augmentation.
This presentation has been archived in the TTU Mediasite catalog ...
mediacast.ttu.edu/Mediasite/Play/40e41fa08bed4e82b7561dbe488046981d
Department of Mathematics & Statistics
-
Address
Texas Tech University, 1108 Memorial Circle, Lubbock, TX 79409-1042 -
Phone
806.742.2566 -
Email
math.dept@ttu.edu