
Quick Links
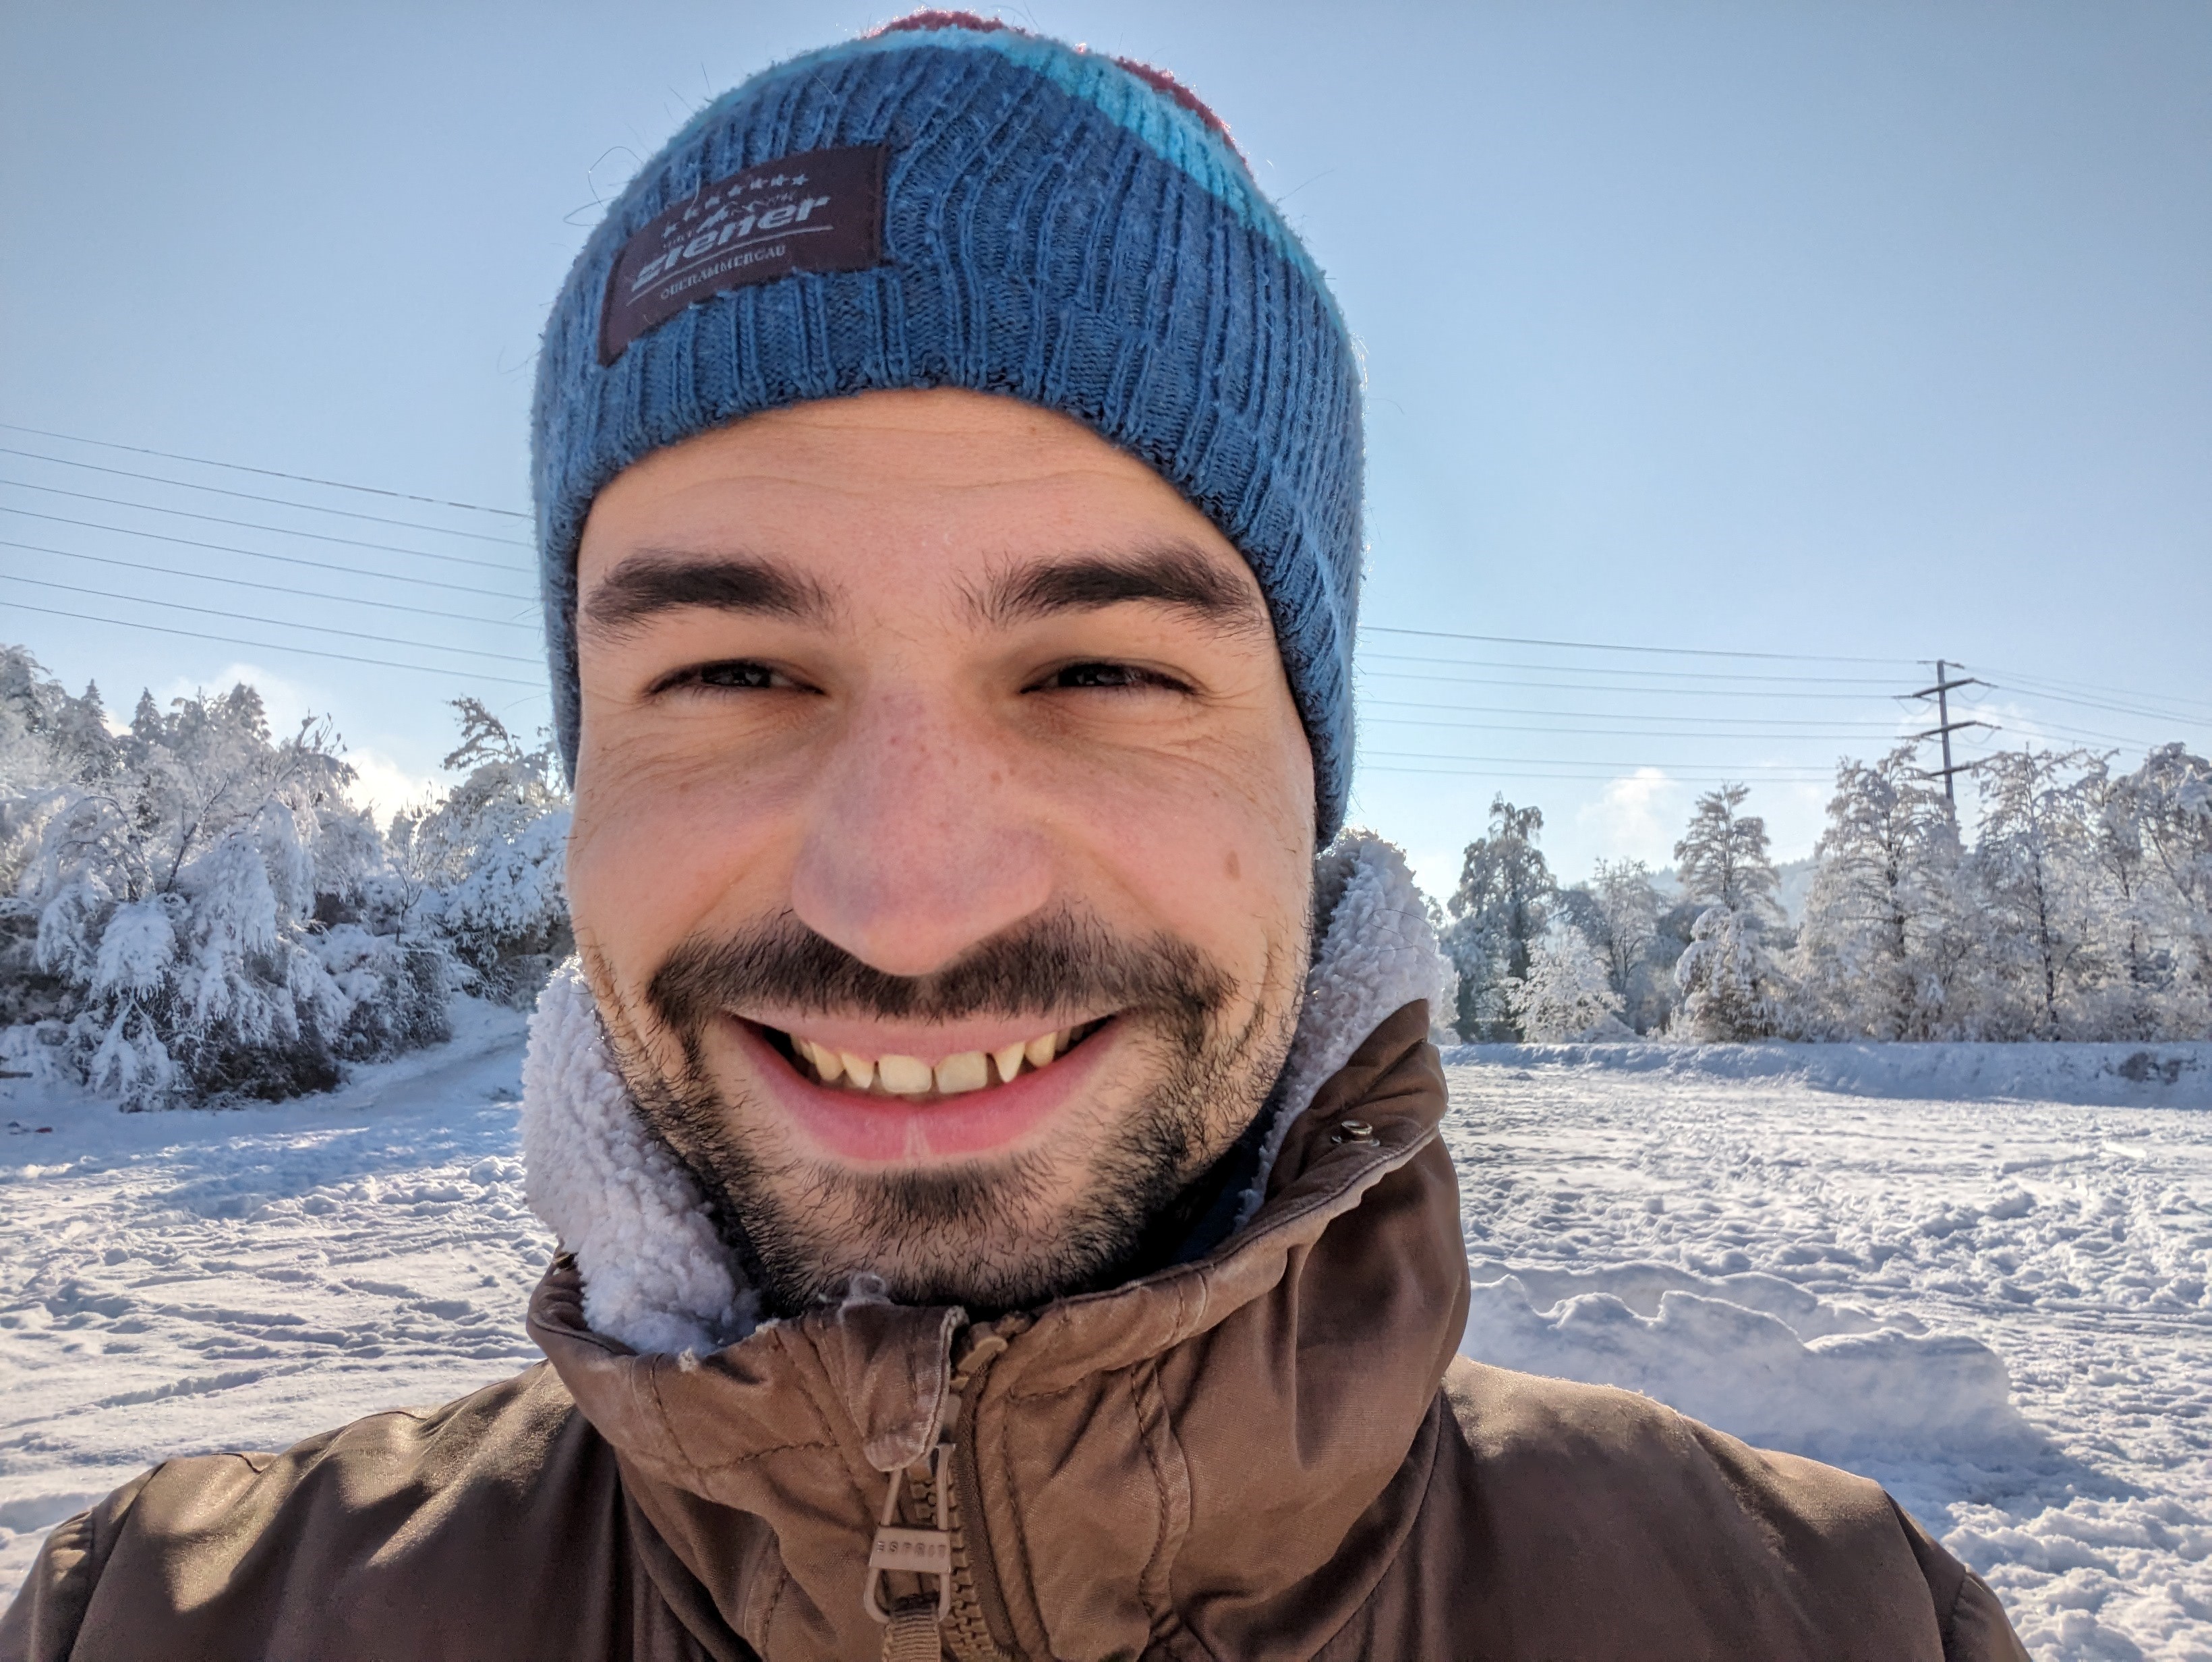
Convergence of the fixed-point iteration for the Bass Local Volatility modelDr. Gudmund Pammer - Dept. of Mathematics, ETH Zürich
Date:
Friday, Jan. 12, 2024
12:00 PM—1:00 PMLocation:
online
Friday, Jan. 12, 2024
12:00 PM—1:00 PMLocation:
online
Convergence of the fixed-point iteration for the Bass Local Volatility modelDr. Gudmund Pammer - Dept. of Mathematics, ETH Zürich
The Bass local volatility model introduced by Backhoff-Veraguas–Beiglböck–Huesmann–Källblad is a Markov model perfectly calibrated to vanilla options at finitely many maturities, that approximates the Dupire local volatility model. Conze and Henry-Labordère show that its calibration can be achieved by solving a fixed-point nonlinear integral equation. We complement the analysis and show, under suitable assumptions, existence and uniqueness of the solution to this equation, and establish that the fixed-point iteration scheme converges at linear rate.
The talk is based on joint work with Beatrice Acciaio and Antonio Marini.
Department of Mathematics & Statistics
-
Address
Texas Tech University, 1108 Memorial Circle, Lubbock, TX 79409-1042 -
Phone
806.742.2566 -
Email
math.dept@ttu.edu