
Quick Links
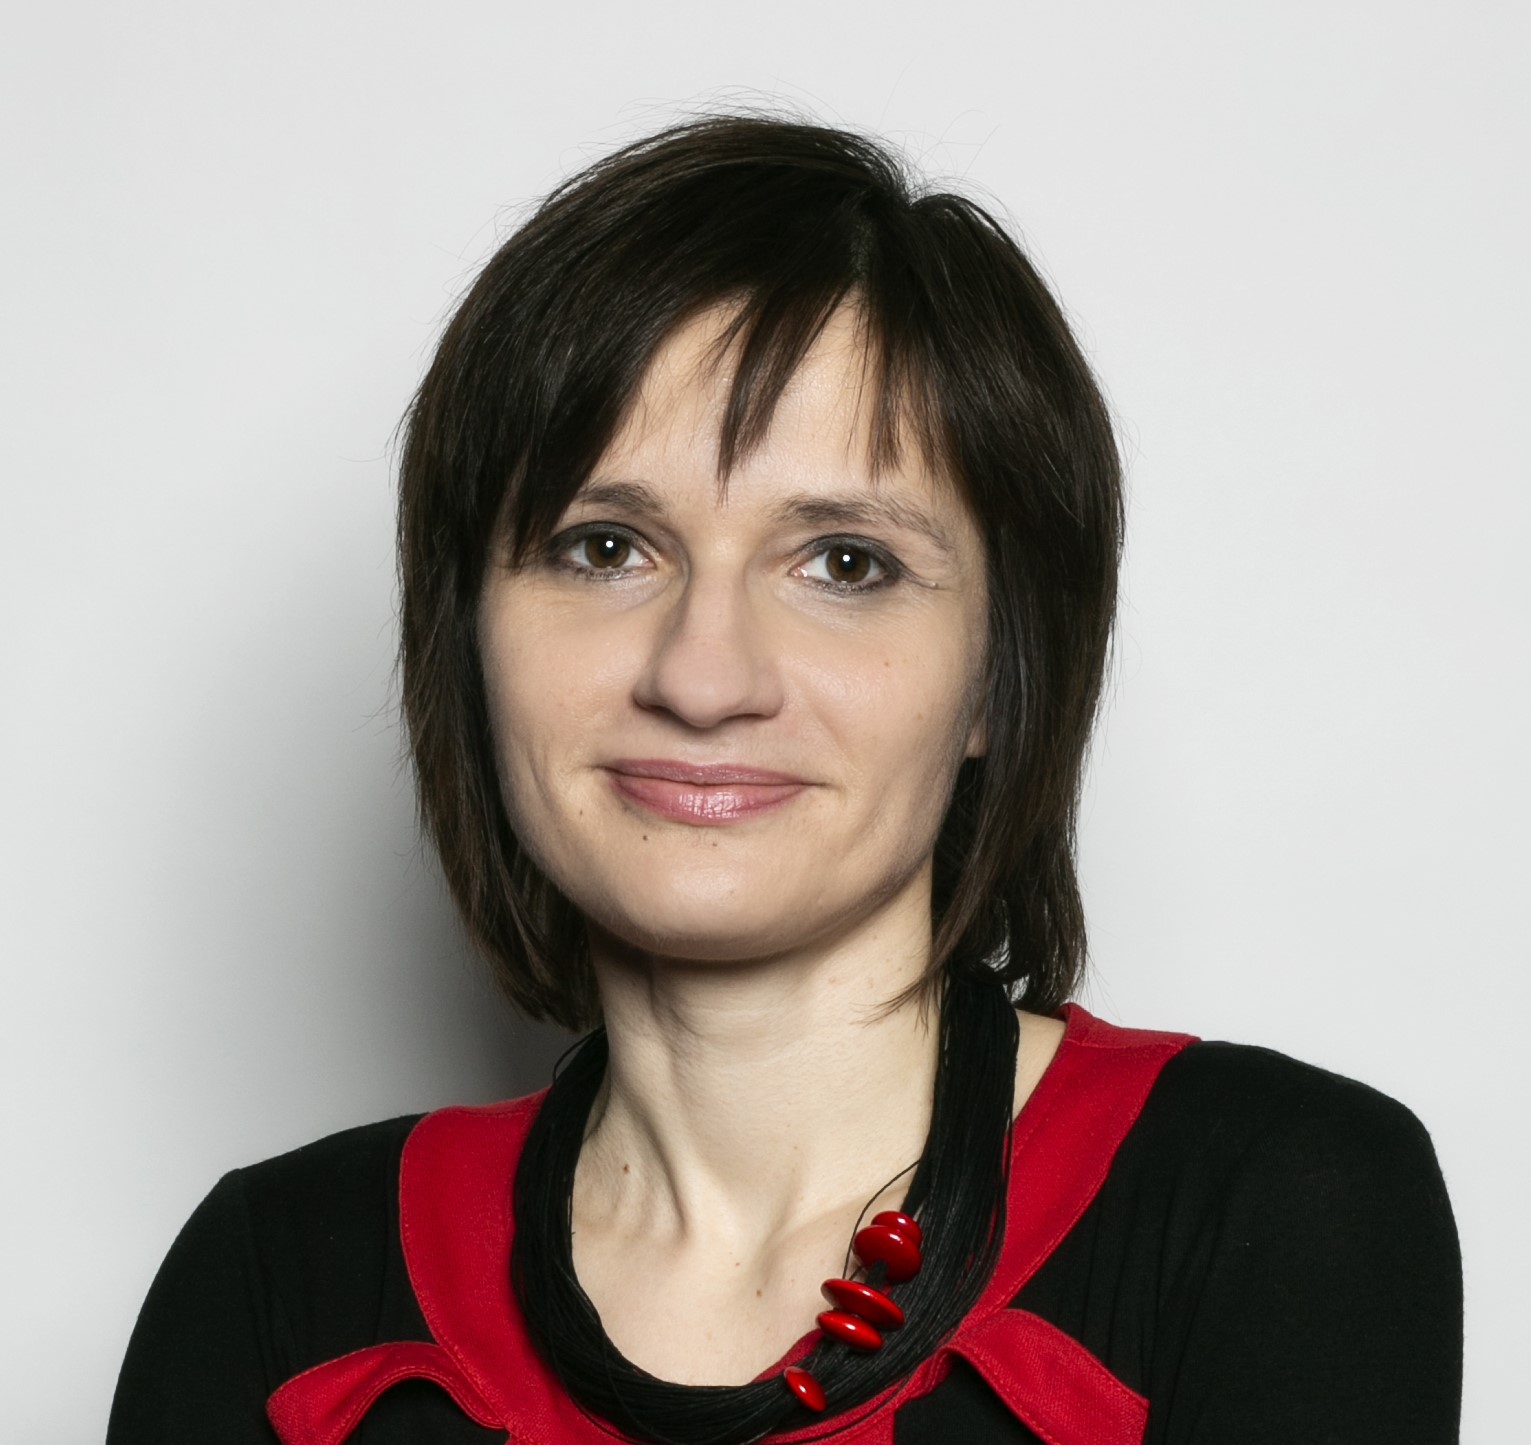
To hedge or not to hedge? Cryptocurrencies, gold and oil against stock market riskProf. Agata Kliber - Dept of Applied Mathematics, Poznan University of Economics & Business, Poznan University of Life Sciences
Date:
Friday, Sep. 20, 2024
12:00 PM—1:00 PMLocation:
online
Friday, Sep. 20, 2024
12:00 PM—1:00 PMLocation:
online
To hedge or not to hedge? Cryptocurrencies, gold and oil against stock market riskProf. Agata Kliber - Dept of Applied Mathematics, Poznan University of Economics & Business, Poznan University of Life Sciences
The article aims to determine whether any hedging strategy against stock market risk, performed using instruments popular in the literature (gold, cryptocurrencies and oil), can beat index futures. As a hedging strategy, we understand a pair-wise portfolio consisting of a long position in stocks and a short position in a hedging instrument put together to minimise the portfolio variance. As a benchmark, we analyse optimal and naive hedging strategies with futures contracts. We demonstrate that, regardless of the stock market, the best hedging strategy focused on variance minimisation requires using index futures. Both strategies: the optimisation-based one and the naive one, beat the dynamic strategies utilising the remaining hedging assets. Therefore, from a risk-minimisation point of view, investors have no motivation to implement cryptocurrencies, gold or oil in hedging strategy against stock market risk. The results are robust with respect to hedging against tail risk.
Co-authors: Prof. Krzysztof Echaust (Dept. of Operations Research & Mathematical Economics, Poznan University of Economics & Business); Prof. Malgorzata Just (Dept. of Finance & Accounting).
Department of Mathematics & Statistics
-
Address
Texas Tech University, 1108 Memorial Circle, Lubbock, TX 79409-1042 -
Phone
806.742.2566 -
Email
math.dept@ttu.edu