
Quick Links
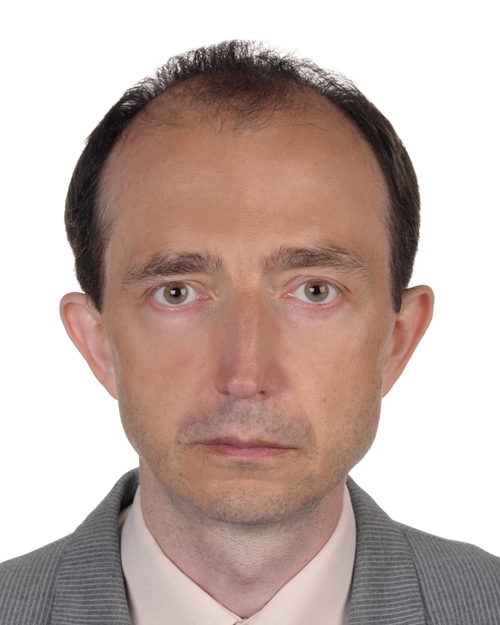
Robust estimation of the range-based GARCH model: Forecasting volatility, value at risk and expected shortfall of cryptocurrenciesProf. Piotr Fiszeder - Dept. Econ. & Stat., Nicolaus Copernicus Univ., Torun, Poland
Date:
Friday, Jan. 24, 2025
1:00 PM—2:00 PMLocation:
online
Friday, Jan. 24, 2025
1:00 PM—2:00 PMLocation:
online
Robust estimation of the range-based GARCH model: Forecasting volatility, value at risk and expected shortfall of cryptocurrenciesProf. Piotr Fiszeder - Dept. Econ. & Stat., Nicolaus Copernicus Univ., Torun, Poland
Traditional volatility models do not work well when volatility changes rapidly and in the presence of outliers. Therefore, two lines of improvements have been developed separately in the existing literature. Range-based models benefit from efficient volatility estimates based on low and high prices, while robust methods deal with outliers. We propose a range-based GARCH model with a bounded M-estimator, which combines these two improvements with a third new improvement: a modified robust method, which adds elasticity in treating the outliers. We apply this model to Bitcoin, Ethereum Classic, Ethereum, and Litecoin and find that it forecasts variances, value at risk, and expected shortfall more accurately than the standard GARCH model, the standard range-based GARCH model, and the GARCH model with the robust estimation. Utilization of high and low prices joined with a novel treatment of outliers makes our model perform well during extreme periods when traditional volatility models fail.
This work is joint with
Prof. Marta Malecka, Faculty of Economics and Sociology, University of Łódź, Łódź, Poland
and
Peter Molnár, UiS Business School, University of Stavanger, Stavanger, Norway.
Department of Mathematics & Statistics
-
Address
Texas Tech University, 1108 Memorial Circle, Lubbock, TX 79409-1042 -
Phone
806.742.2566 -
Email
math.dept@ttu.edu