
Quick Links
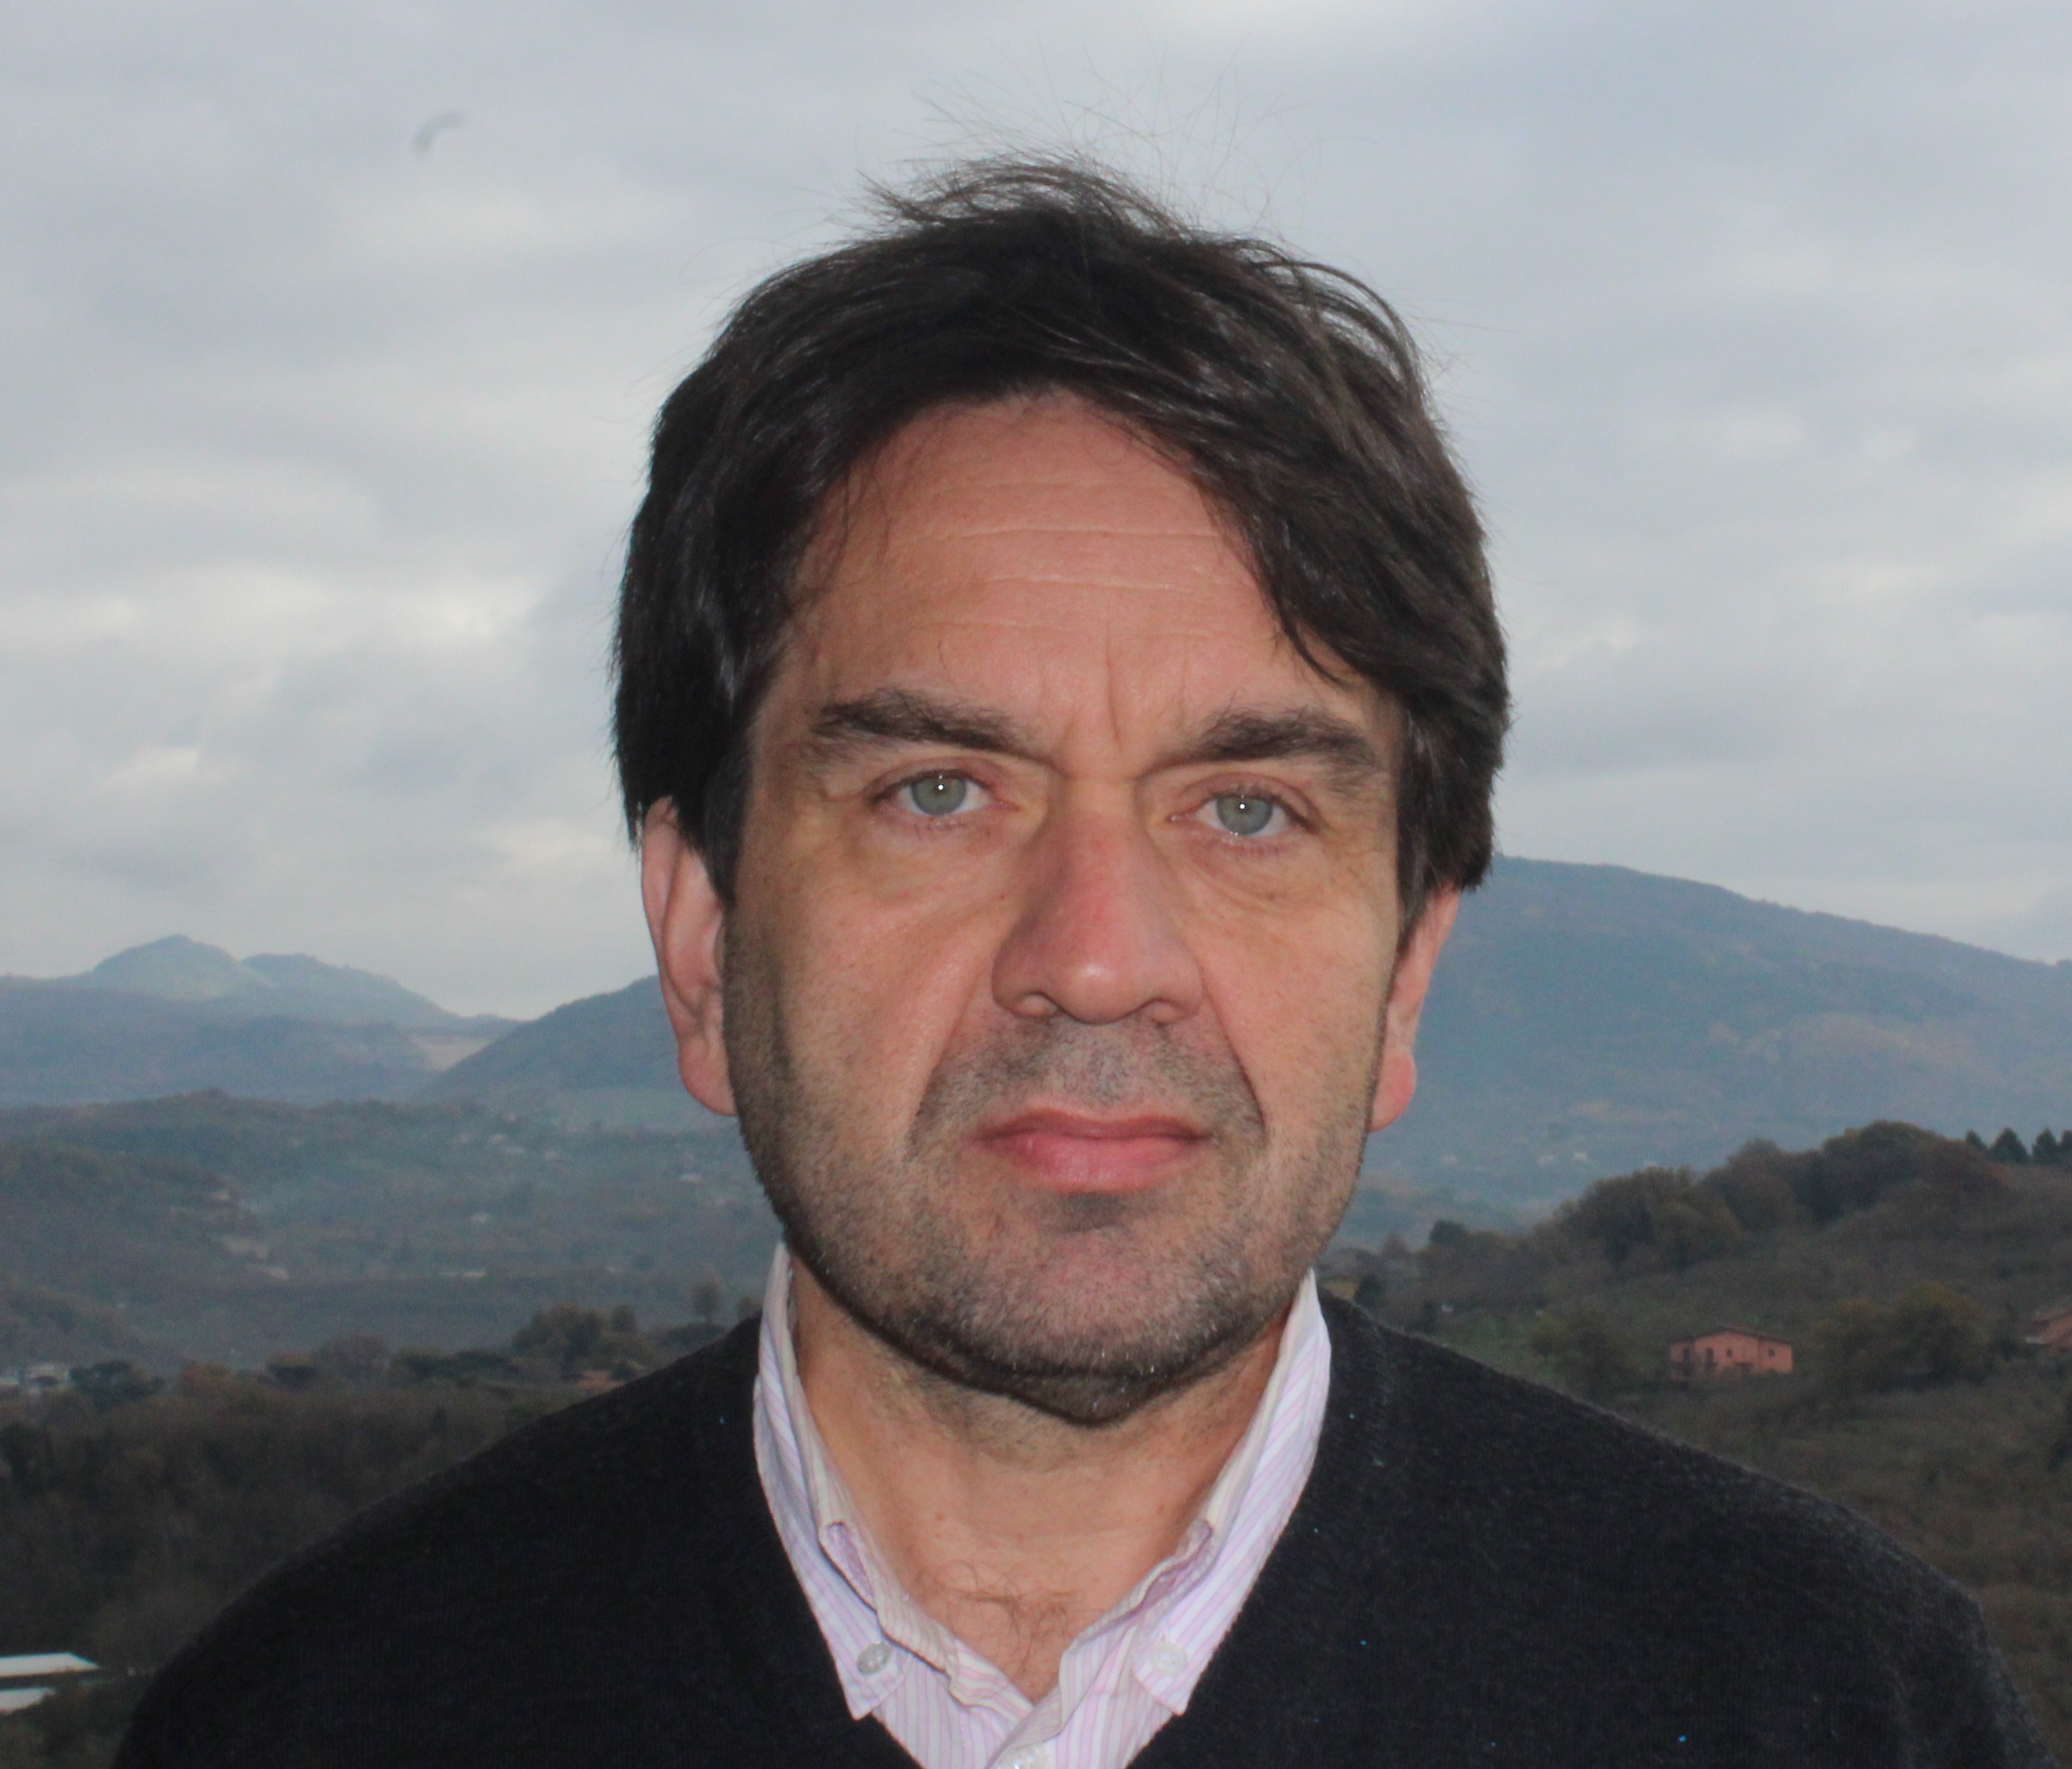
Dynamic tail risk forecasting: What do realized skewness and kurtosis add?Prof. Giuseppe Storti - Dept. Econ & Stat., University of Salerno, Fisciano, IT
Date:
Friday, Mar. 14, 2025
12:00 PM—1:00 PMLocation:
online
Friday, Mar. 14, 2025
12:00 PM—1:00 PMLocation:
online
Dynamic tail risk forecasting: What do realized skewness and kurtosis add?Prof. Giuseppe Storti - Dept. Econ & Stat., University of Salerno, Fisciano, IT
This paper compares the accuracy of tail risk forecasts with a focus on including realized skewness and kurtosis in ”additive” and ”multiplicative” models. Utilizing a panel of 960 US stocks, we conduct diagnostic tests, employ scoring functions, and implement rolling window forecasting to evaluate the performance of Value at Risk (VaR) and Expected Shortfall (ES) forecasts. Additionally, we examine the impact of the window length on forecast accuracy. We propose model specifications that incorporate realized skewness and kurtosis for enhanced precision. Our findings provide insights into the importance of considering skewness and kurtosis in tail risk modeling, contributing to the existing literature and offering practical implications for risk practitioners and researchers.
Department of Mathematics & Statistics
-
Address
Texas Tech University, 1108 Memorial Circle, Lubbock, TX 79409-1042 -
Phone
806.742.2566 -
Email
math.dept@ttu.edu