
Quick Links
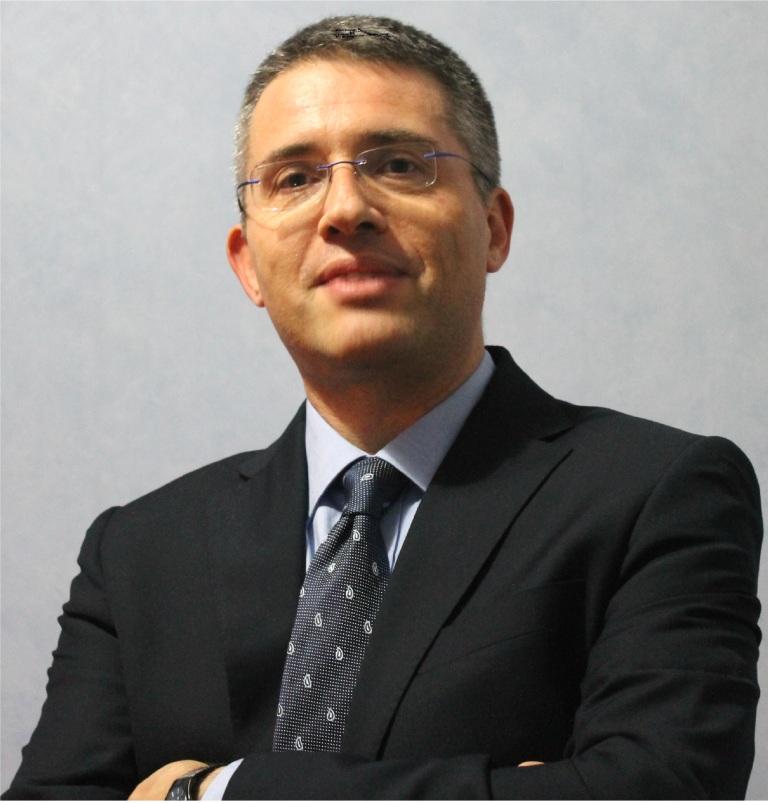
Beyond Traditional Models: Assessing the Role of LSTM Networks in Volatility PredictionProf. Massimo Guidolin - Baffi Carefin Center, Bocconi Univ., Milan
Date:
Friday, Oct. 10, 2025
12:00 PM—1:00 PMLocation:
online
Friday, Oct. 10, 2025
12:00 PM—1:00 PMLocation:
online
Beyond Traditional Models: Assessing the Role of LSTM Networks in Volatility PredictionProf. Massimo Guidolin - Baffi Carefin Center, Bocconi Univ., Milan
This paper examines the out-of-sample accuracy of recurrent artificial neural networks (ANNs) compared to traditional econometric models for the prediction of realized volatility. We focus on a horserace between the heterogeneous autoregressive (HAR) model, its Markov-switching extension (MS-HAR), multi-layer perceptrons (MLP), and long short-term memory (LSTM) networks across 31 international equity indices. Using high-frequency realized volatility data, we evaluate predictive performance based on four loss functions and test for equal accuracy using Diebold-Mariano tests. Our results suggest that the HAR and MS-HAR models often deliver the most accurate forecasts, outperforming LSTMs. However, differences in out-of-sample accuracy between LSTM, HAR, and MS-HAR models are not always statistically significant. We conclude that ANNs do not consistently outperform HAR-based models in equity volatility forecasting.
Department of Mathematics & Statistics
-
Address
Texas Tech University, 1108 Memorial Circle, Lubbock, TX 79409-1042 -
Phone
806.742.2566 -
Email
math.dept@ttu.edu