
Quick Links
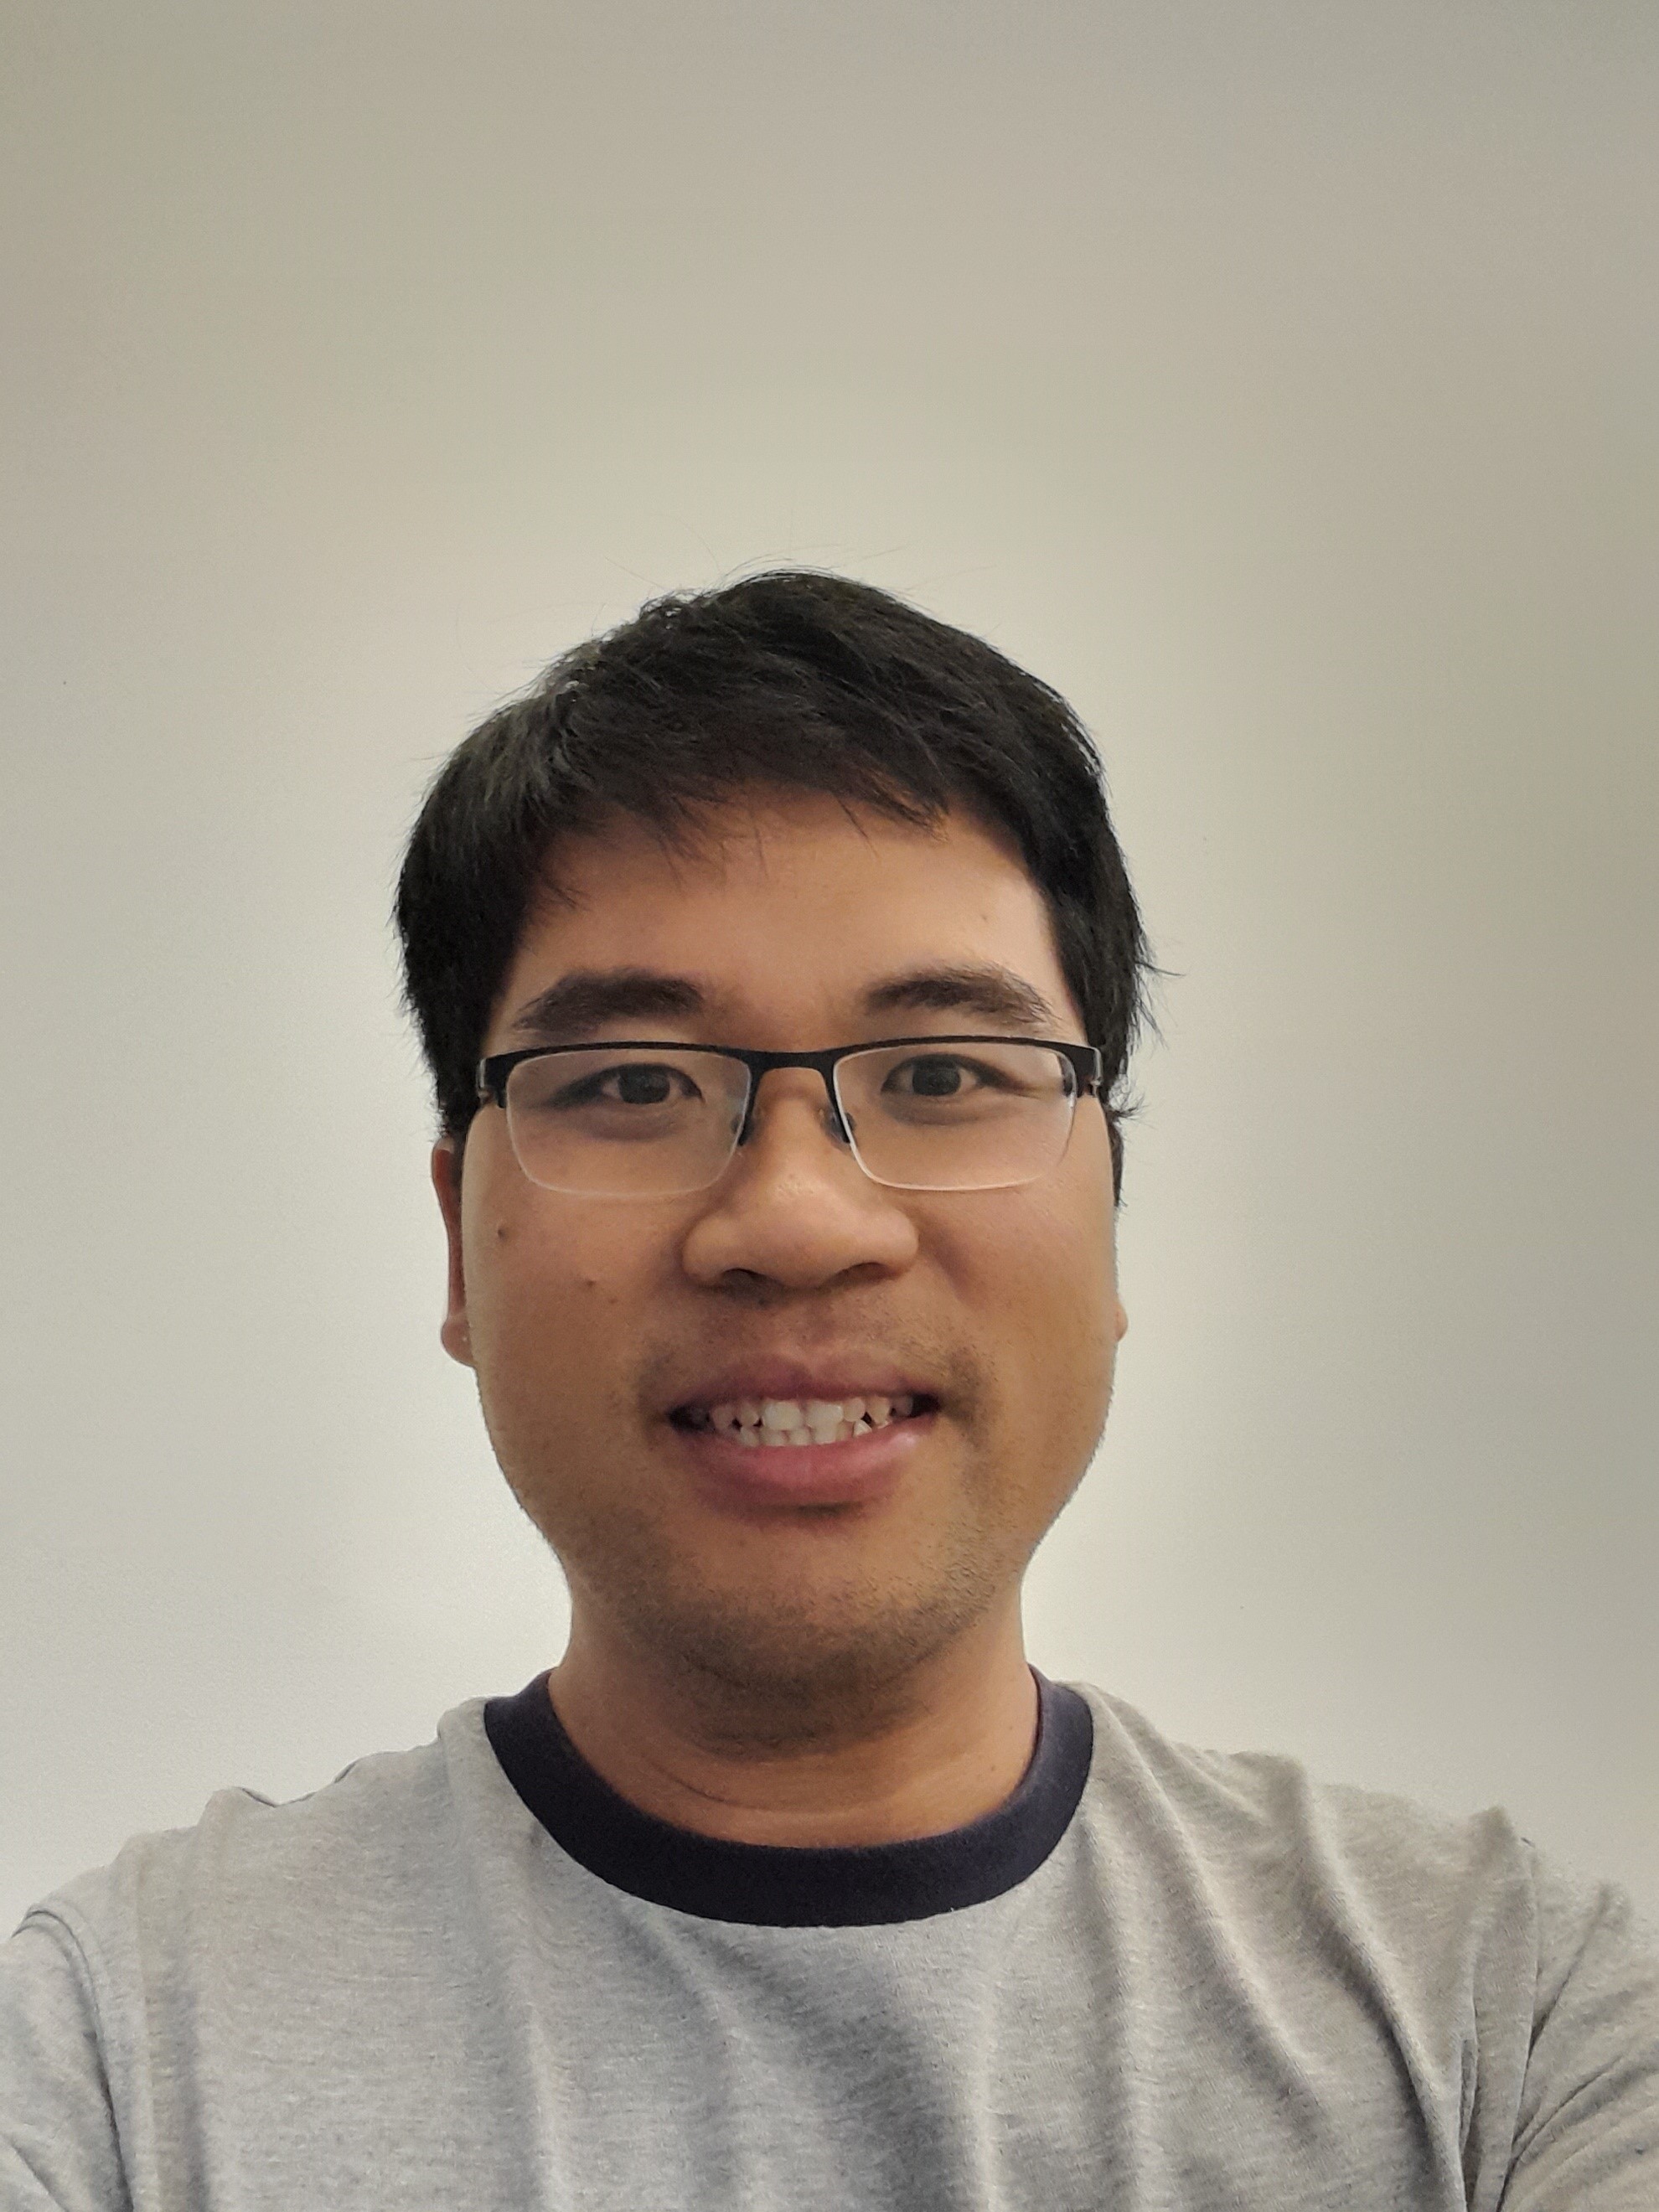
A general framework for pricing and hedging under local viabilityProf. Huy Chau - Dept. Mathematics, University of Manchester
Date:
Friday, Oct. 31, 2025
12:00 PM—1:00 PMLocation:
online
Friday, Oct. 31, 2025
12:00 PM—1:00 PMLocation:
online
A general framework for pricing and hedging under local viabilityProf. Huy Chau - Dept. Mathematics, University of Manchester
In this paper, a new approach for solving the problems of pricing and hedging derivatives is introduced in a general frictionless market setting. The method is applicable even in cases where an equivalent local martingale measure fails to exist. Our main results include a new superhedging duality for American options when wealth processes can be negative and trading strategies are subject to a cone constraint. This answers one of the questions raised by Fernholz, Karatzas and Kardaras.
Department of Mathematics & Statistics
-
Address
Texas Tech University, 1108 Memorial Circle, Lubbock, TX 79409-1042 -
Phone
806.742.2566 -
Email
math.dept@ttu.edu