
Quick Links
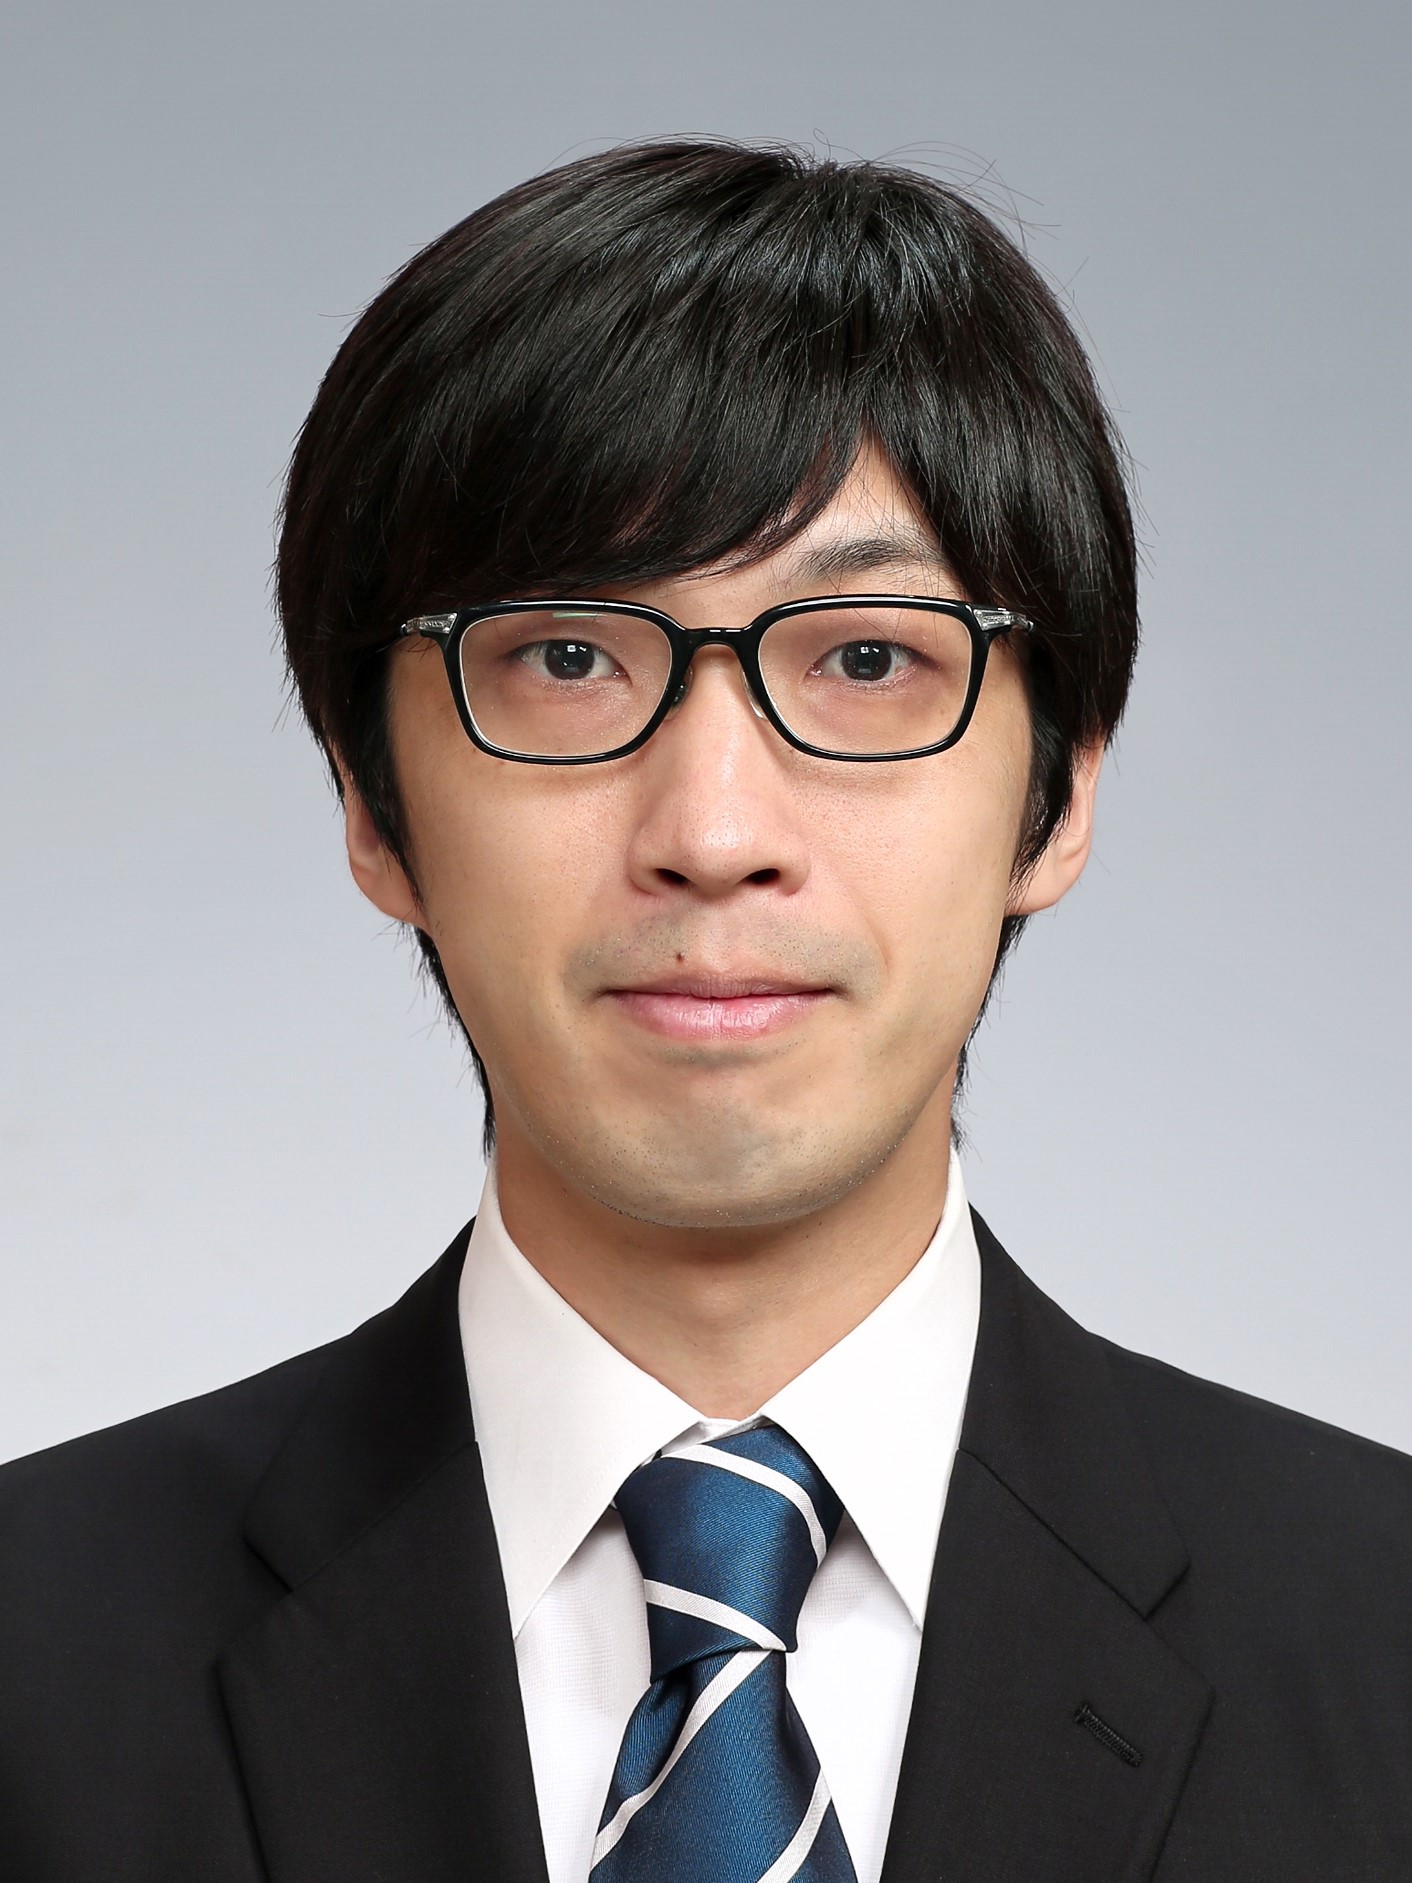
Dynamic asymmetric tail dependence structure among multi-asset classes for portfolio management: Dynamic skew- copula approachDr. Kakeru Ito - Senior Portfolio Manager (Multi-Asset / Quants), Mizuho Securities Co., Ltd. and Visiting Researcher, Graduate School of Management, Tokyo Metropolitan University
Date:
Friday, Apr. 24, 2026
9:00 AM—10:00 AMLocation:
online
Friday, Apr. 24, 2026
9:00 AM—10:00 AMLocation:
online
Dynamic asymmetric tail dependence structure among multi-asset classes for portfolio management: Dynamic skew- copula approachDr. Kakeru Ito - Senior Portfolio Manager (Multi-Asset / Quants), Mizuho Securities Co., Ltd. and Visiting Researcher, Graduate School of Management, Tokyo Metropolitan University
This study proposes AC dynamic skew-𝑡 copula with cDCC model to capture the dynamic asymmetric tail dependence structure among multi-asset classes (government bonds, corporate bonds, equities, and REITs). We provide new evidence that lower tail dependence coefficients increased compared to upper ones for all pairs in the COVID-19 crash and the recent high inflation period, indicating that the diversification effect through multi-asset investment decreased. Our empirical analysis also shows that in terms of AIC and BIC, dynamic AC skew-𝑡 copula fits data of multi-asset classes better than other dynamic elliptical copulas because it can consider the above dependence structure characteristics. Furthermore, out-of-sample analysis reveals that considering an asymmetry of tail dependence structure at each point with an AC dynamic skew-𝑡 copula enhances expected shortfall (ES) estimation accuracy and the performance of a minimum ES portfolio. These results indicate that capturing dynamic asymmetric tail dependence is crucial for multi-asset portfolio management.
Department of Mathematics & Statistics
-
Address
Texas Tech University, 1108 Memorial Circle, Lubbock, TX 79409-1042 -
Phone
806.742.2566 -
Email
math.dept@ttu.edu