
Quick Links
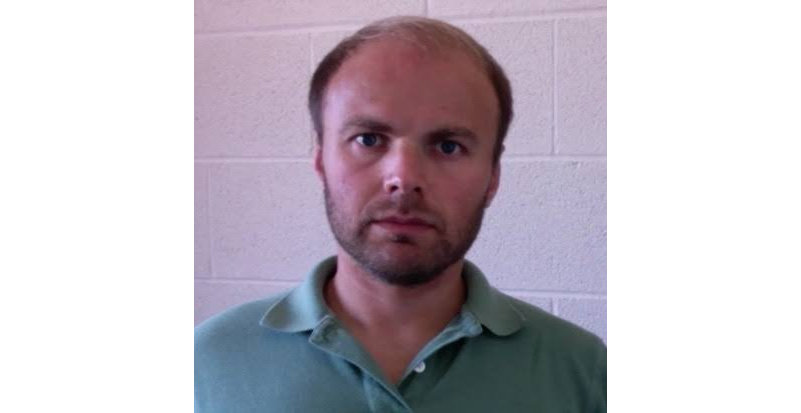
Stochastic Dominance, Analyticity, and High-Order Expansions in Optimal InvestmentOleksii Mostovyi - Mathematics, University of Connecticut
Date:
Friday, Oct. 9, 2026
2:00 AMLocation:
online
Friday, Oct. 9, 2026
2:00 AMLocation:
online
Stochastic Dominance, Analyticity, and High-Order Expansions in Optimal InvestmentOleksii Mostovyi - Mathematics, University of Connecticut
We study higher-order regularity and sensitivity of utility maximization in incomplete financial markets. The starting point is a class of preferences characterized by completely monotone inverse marginal utilities and a corresponding stochastic-dominance property of the market. In earlier joint work with Mihai Sîrbu and Thaleia Zariphopoulou, we showed that, under this structure, analyticity of preferences is inherited by the value function and obtained explicit representations for higher-order derivatives of the value function and the optimizer.
I will then discuss recent joint work with Thaleia Zariphopoulou on perturbations of investor preferences. Using Bernstein's representation of completely monotone functions, affine perturbations of the representing measures lead to a hidden affine structure in the dual optimization problem. The key step in the sensitivity analysis is the study of a scalar implicit equation for the Lagrange multiplier. We establish analyticity with respect to the perturbation parameter and derive recursive high-order expansions for the value function and optimal terminal wealth. The coefficients are expressed explicitly through Bell polynomials.
The talk will emphasize the roles of stochastic dominance, complete monotonicity, and convex duality in making otherwise nonlinear sensitivity problems tractable.
Department of Mathematics & Statistics
-
Address
Texas Tech University, 1108 Memorial Circle, Lubbock, TX 79409-1042 -
Phone
806.742.2566 -
Email
math.dept@ttu.edu